Front Office
Release 26.10

CDS Index Options in SimCorp One Trader
Front-office trading teams can manage and trade CDS Index Options end to end within the Order Manager, handling the full order lifecycle in the SimCorp One Trader.
Coverage spans both cleared and bilateral CDS Index Options. Because options flow through the same order process as every other instrument, pre-trade compliance is applied automatically, and the key pre-modelled option attributes — such as strike, expiry and details of the CDS index — are shown to the trader in SimCorp One Trader.
When capturing a trade, it is possible to optionally enter pre- and post- delta-adjusted premium and adjust the strike to allow for solve-for strikes.
Benefits
- Enable trading desks to manage and trade CDS Index Options end to end within a single, consolidated order book.
Subscription based licensing
N/A
Sales module dependency
Order Manager
Cross-currency interest rate swaps in SimCorp One Trader
Front-office trading teams can manage and trade cross-currency interest rate swaps end to end within the Order Manager, handling the full order lifecycle in the SimCorp One Trader.
Coverage spans both deliverable and non-deliverable swaps. Because swaps flow through the same order process as every other instrument, pre-trade compliance is applied automatically, and the key pre-modelled swap attributes — such as currencies, indices and dates— are shown to the trader in SimCorp One Trader.
When capturing a trade, for swaps traded on NPV (i.e. with a net amount) it is possible to enter the NPV in the settlement currency of either leg.
Benefits
- Enable trading desks to manage and trade cross-currency interest rate swaps end to end within a single, consolidated order book.
Subscription based licensing
N/A
Sales module dependency
Order Manager
Browse the Release Portal
Release 26.07
OTC FX Options in the Order Manager
Front-office trading teams can manage and trade OTC FX Options end to end within the Order Manager, handling the full order lifecycle in the SimCorp One Order Manager.
Coverage spans multiple variants — Vanilla, Digital, Single Barrier, Double Barrier, and Touch. Vanilla options can be traded electronically with straight-through processing to FXAll over FIX, while the full set can be captured manually, so every variant lives in one consolidated order book. Because options flow through the same order process as every other instrument, pre-trade compliance is applied automatically, and the key pre-modeled option attributes — such as strike, expiry, and expiry time zone — are shown to the trader in Order Manager.
Multi-leg strategies build on SimCorp’s established contingency model, in which orders are linked by a unique, system-generated ID. This is now extended to set a contingency between OTC and non-OTC orders — for example an FX Option with its FX Spot or FX Forward hedge — and to add granularity through a contingent subtype and contingent sub ID.
Benefits
- Enable trading desks to manage and trade the full range of OTC FX Options — from Vanilla through to exotics — end to end within a single, consolidated order book.
- Reduce operational risk and manual effort by trading Vanilla options straight through to FXAll.
- Optimize the handling of multi-leg strategies by keeping every leg, its Bloomberg OVML reference and its delta hedge linked together visually in Order Manager.
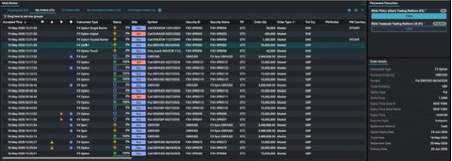
Caption: All variants of OTC FX Options displayed in the SimCorp One Order Manager Order blotter
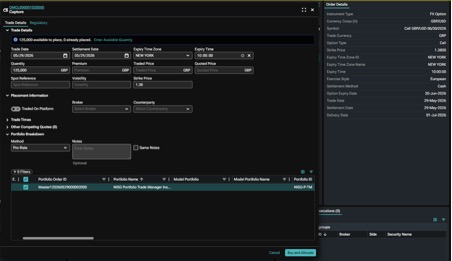
Caption: All variants of OTC FX Options displayed in the SimCorp One Order Manager Order blotter
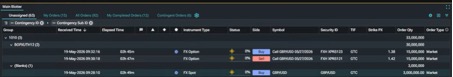
Caption: An FX Option multi-leg strategy displayed in the SimCorp One Order Manager, with the associated FX Spot delta.
Subscription based licensing
Add-on for Order Manager FX
Sales module dependency
Order Manager; FIX connectivity to FXAll (for electronic Vanilla execution); Asset Manager (for multi-leg strategy / contingency set-up)
Removing the requirement to host Bloomberg infrastructure on-premise
With the 26.07 release, Bloomberg's Zero-footprint solution for Server API (SAPI) real-time data is available for streaming data and request/response data in both Asset Manager and Order Manager.
A zero-footprint delivery option gives clients access to data without the previous overhead of installed, on-premise Bloomberg infrastructure. All required Bloomberg software is hosted on the Bloomberg cloud within Bloomberg’s highly resilient global network, and clients access data via secure internet connectivity using the Bloomberg API. This option is available to applications regardless of where they reside, including all public clouds.
Benefits
- Removes overhead of hosting Bloomberg infrastructure on-premise
- Available on both public cloud and private cloud
- Same access to real-time data as existing hosted solution
- Dedicated regional Bloomberg endpoints
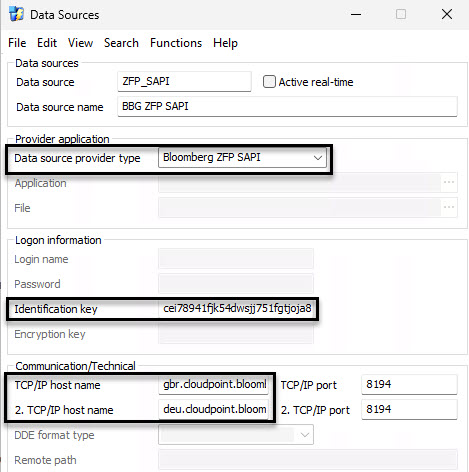
Caption: Data Source setup for Bloomberg Zero-footprint SAPI
Subscription based licensing
Asset Manager, Order Manager
Sales module dependency
Asset Manager - Base, Order Manager
Release 26.01

Portfolio Analysis – AI-Powered Portfolio Viewing Capabilities
This is a cloud-native evolution of Asset Manager, designed to enhance decision-making, streamline workflows, and unlock new analytics capabilities. You can view the positions and analytics supported by the visualizations as of today and as for a historical date.
Benefits
- Fast web access to view your data anytime, anywhere.
- Intuitive design for smooth navigation and visualisation.
- Leverage Generative AI for smarter, faster data analysis.
- Dive into time-series data with easy historical browsing.
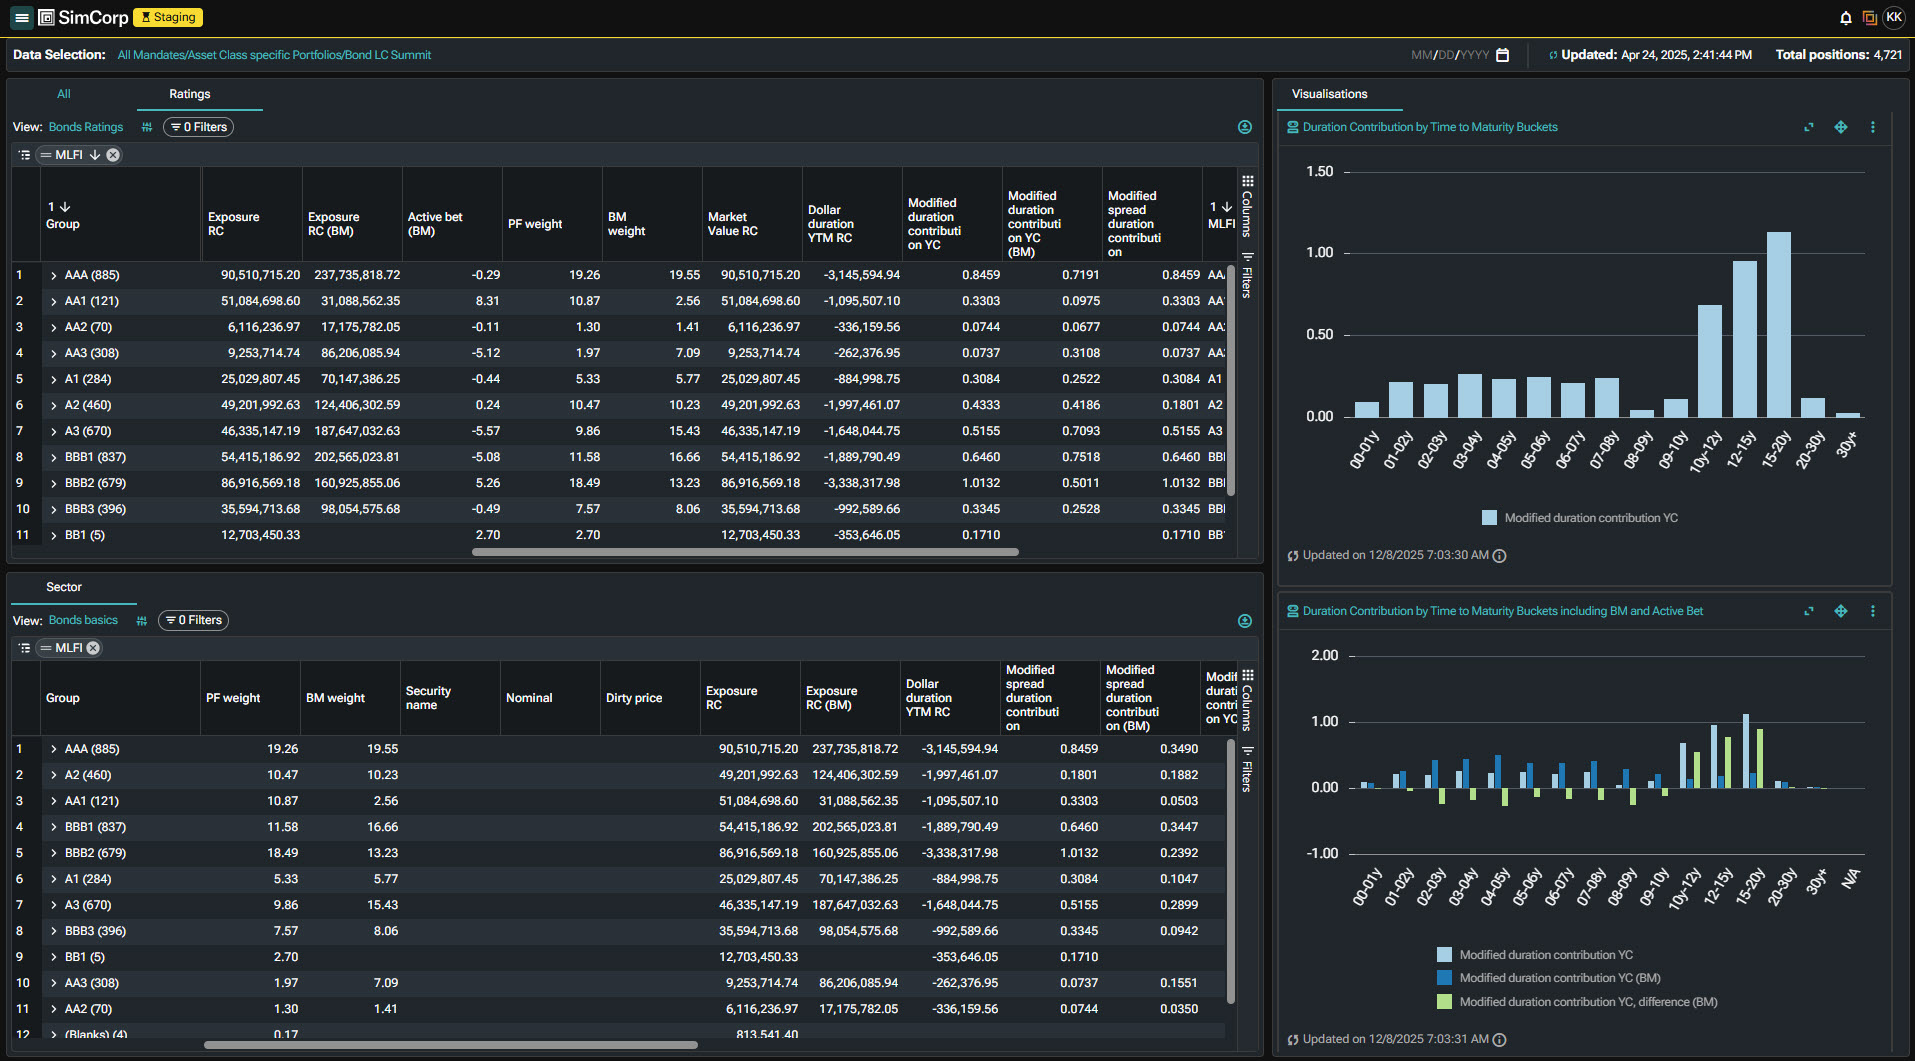
Caption: Next Gen AI-Powered Portfolio Viewing Capabilities in Dark Theme
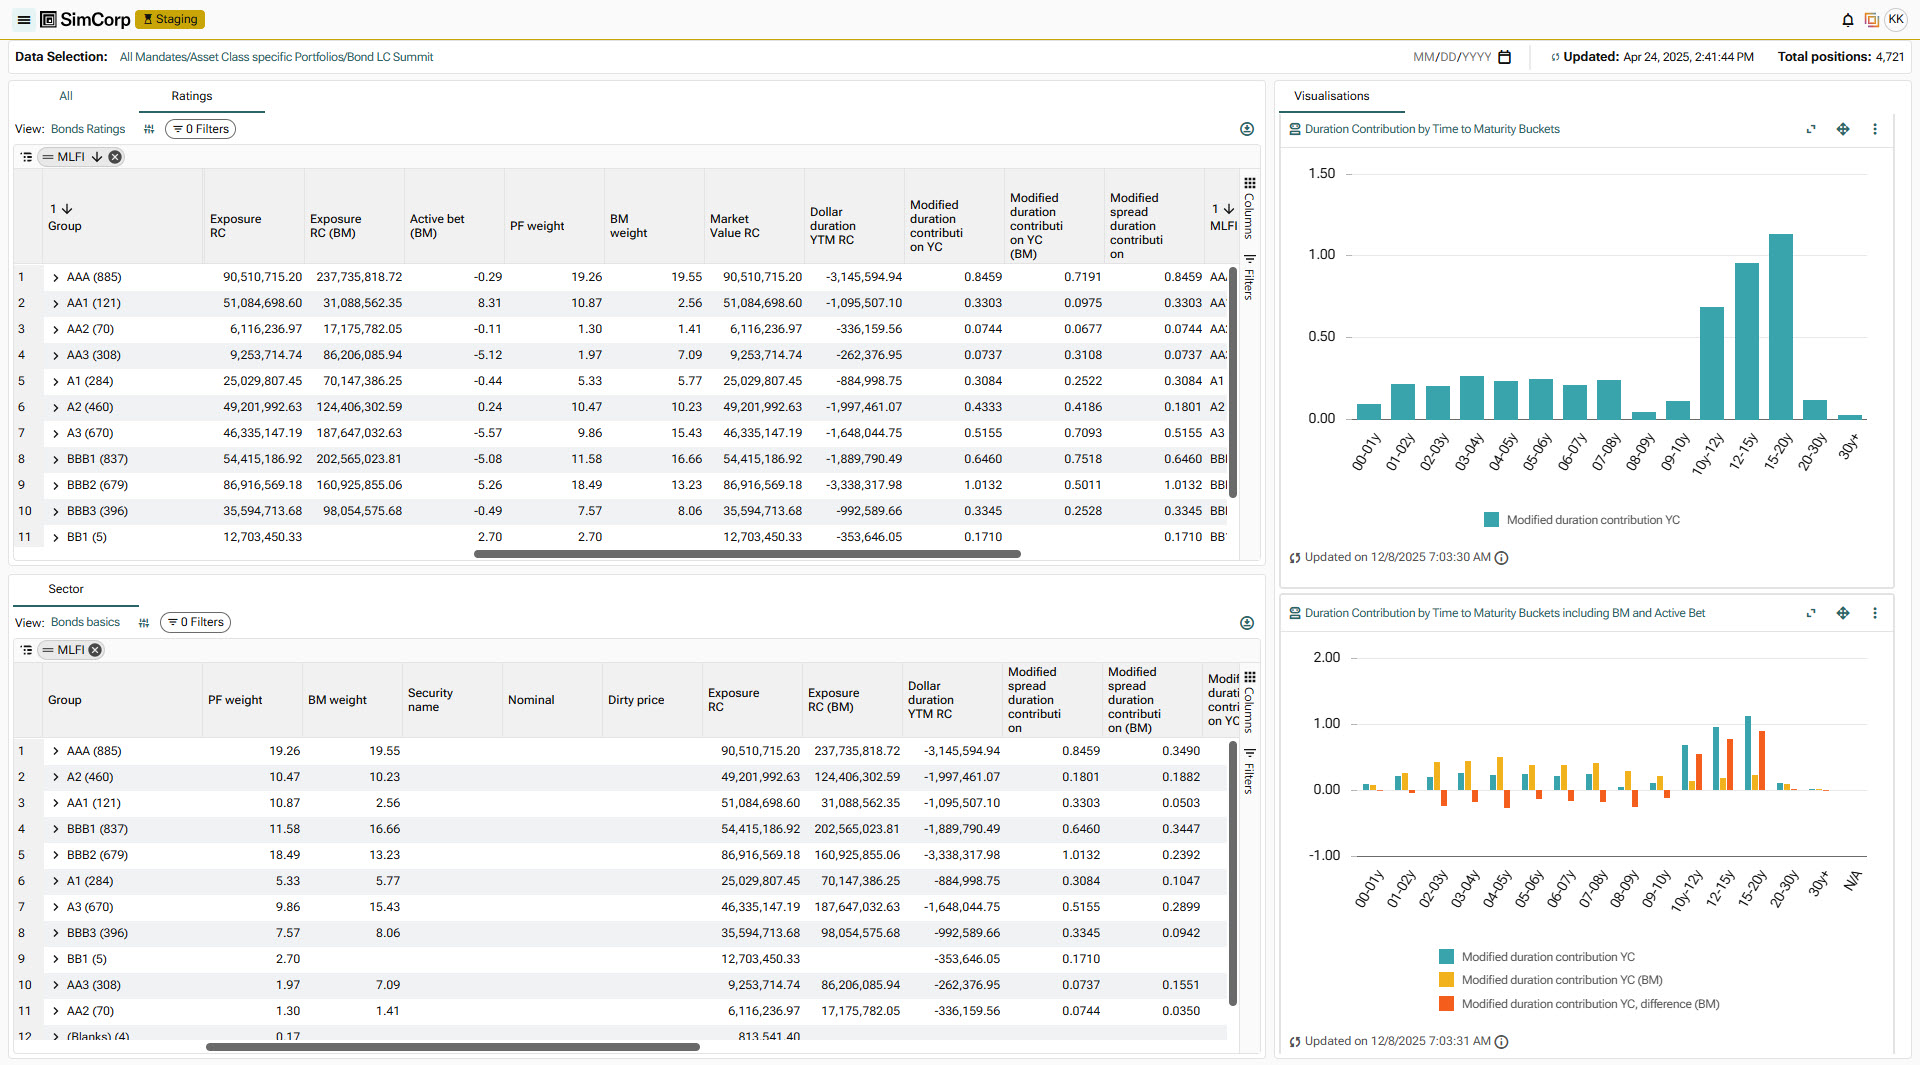
Caption: Next Gen AI-Powered Portfolio Viewing Capabilities in Light Theme
Subscription based licensing
Next Gen Asset Manager, Copilot, Front Office API
Sales module dependency
Asset Manager - Base, Asset Manager API
Simple End-of-Period Reporting of Investment Restrictions
Version 25.10 of Compliance Manager brings a dedicated web API for easy end-of-period reporting of investment restrictions.
The API highly simplifies the retrieval of post-trade compliance results. This reduces implementation time and removes the need to understand the structure of the underlying database.
With just a few parameters, you can query portfolio or mandate level results, or dive into the individual results for detailed reporting of breached investment restrictions.
To improve the operational workflow, the API further enables you to detect upstream issues early and query for updated results in case some post-trade validations have been rerun.
Benefits
- Reduced implementation time of reporting solutions
- No need for SQL competences
- Simplified operational workflow
- Improved security as directly database access is not required
Subscription based licensing
Compliance Manager
Sales module dependency
N/A
Release 20.10
Release 25.07 - Front Office
Input Fields in the Asset Manager
Enablement of stronger portfolio construction workflows
With the 25.07 release, we have introduced new input fields in the Asset Manager, enabling the creation of even more flexible and powerful construction workflows.
Together with all the attributes and analytics fields in the Asset Manager, we are now introducing user- configurable input fields. In these fields, you can easily type in and edit values, which will be persisted and loaded the next time you open the Asset Manager.
The input fields can be anchored on different levels–security, issuer, sector, portfolio, etc.– and can, for example, represent long-term investment targets, trading signals, or risk appetite.
This may appear like a small thing, but on the back of these input fields, you can build powerful automated portfolio construction workflows. You can create Simulation Macros that take these input field values and run customized, client-specific calculations to create suggested trades. Hereby, you can create some very rich allocation and alignment workflows.
Benefits
- Easy input of values on different levels.
- Persisted for later use.
- Enables creation of much more advanced Simulation Macros using input values from multiple levels for simulation generation.
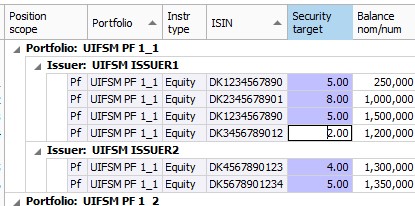
Example of an Input Field in the Asset Manager.
Subscription based licensing
Asset Manager
Sales module dependency
Asset Manager
Release 25.04 - Front Office
Electronic trading (via FIX) of inflation swaps
Inflation swap volumes have increased significantly in recent years, leading to greater uptake of electronic trading in the market. Order Manager now supports electronic trading via FIX of Zero Coupon Inflation Swaps (ZC ILS) on Tradeweb, using the same fast and efficient order flow already available for other instrument types.
Both bilateral and centrally cleared swaps can be traded, and position-closing orders for cleaned positions can also be traded (on NPV).
Benefits
- Enables straight-through-processing of ZC ILS orders, increasing speed of execution and reducing operational risk.
- Regulatory identifiers (allocation and beta USIs) and clearing status are automatically consumed and stored from Tradeweb for reporting and recordkeeping.
- Competing quotes are automatically saved to document best execution.
Subscription based licensing
Order Manager and add-ons
Sales module dependency
Order Manager
Streamlined workflows and enhanced insights
Over the past year, we have partnered with several of our daily users of Compliance Manager to eliminate time-consuming, tedious manual tasks and boost productivity. With version 25.04, we are excited to bring another round of workflow enhancements.
We have brought the pre-trade side into the process of working with post-trade breaches. When working with a post-trade failure in the Alerts Inbox, we now show relevant pre-trade failures and override comments. Often, these comments help explain why a compliance rule fails post-trade.
The presentation of compliance result details has been enriched and made more compact, giving better insights into the evaluation of complex rules.
More visual cues have been added to the action and event history of alerts. For longer-running breaches, this helps maintain oversight and make informed decisions. One possible action is to temporarily approve a breach, which can now be done in more flexible ways.
The daily users of Compliance Manager are the experts on what works well and what can be improved. To make it easier for everyone to contribute their insights, we have added a new feedback feature directly inside Compliance Manager. We invite you to use it and share your feedback with us.
Benefits
- Direct access to pre-trade override comments when working with post-trade breaches
- Enriched result details that enable easier understanding of complex compliance rules
- Additional visual cues on post-trade alerts to, for instance, easily distinguish agreement date-based rules from settlement date-based rules.
Subscription based licensing
Compliance Manager
Sales module dependency
Compliance Manager - Base
Release 25.01 - Front Office
Using Compliance Rules to define Optimization Constraints
The Axioma Portfolio Optimizer is widely used by SimCorp clients to efficiently create quantitative or systematic investment strategies. The quality of the solution and the resulting trade list can be greatly enhanced by improving the accuracy of the data sets.
To date, integration between these products has ensured consistency and precision in portfolio and benchmark positions, prices, and analytics, supported by a shared set of reference data.
The next step has been to add Compliance rules to that list. This ensures that the resulting optimal trades will pass pre-trade compliance checks.
The first phase has focused on “Do Not Invest” lists. E.g., Global sanctions lists, blacklisted ESG securities, specific sectors, or country lists.
Benefits
This resolves the challenge of creating an optimal trade list, only to find that it subsequently fails pre-trade compliance, requiring the process to be re-run. In effect:
- This improves the quality of the solution and trade list.
- Reduces the number of iteration to get to a solution
- Allows a single system to manage constraints and compliance rule sets with the requisite auding and controls.
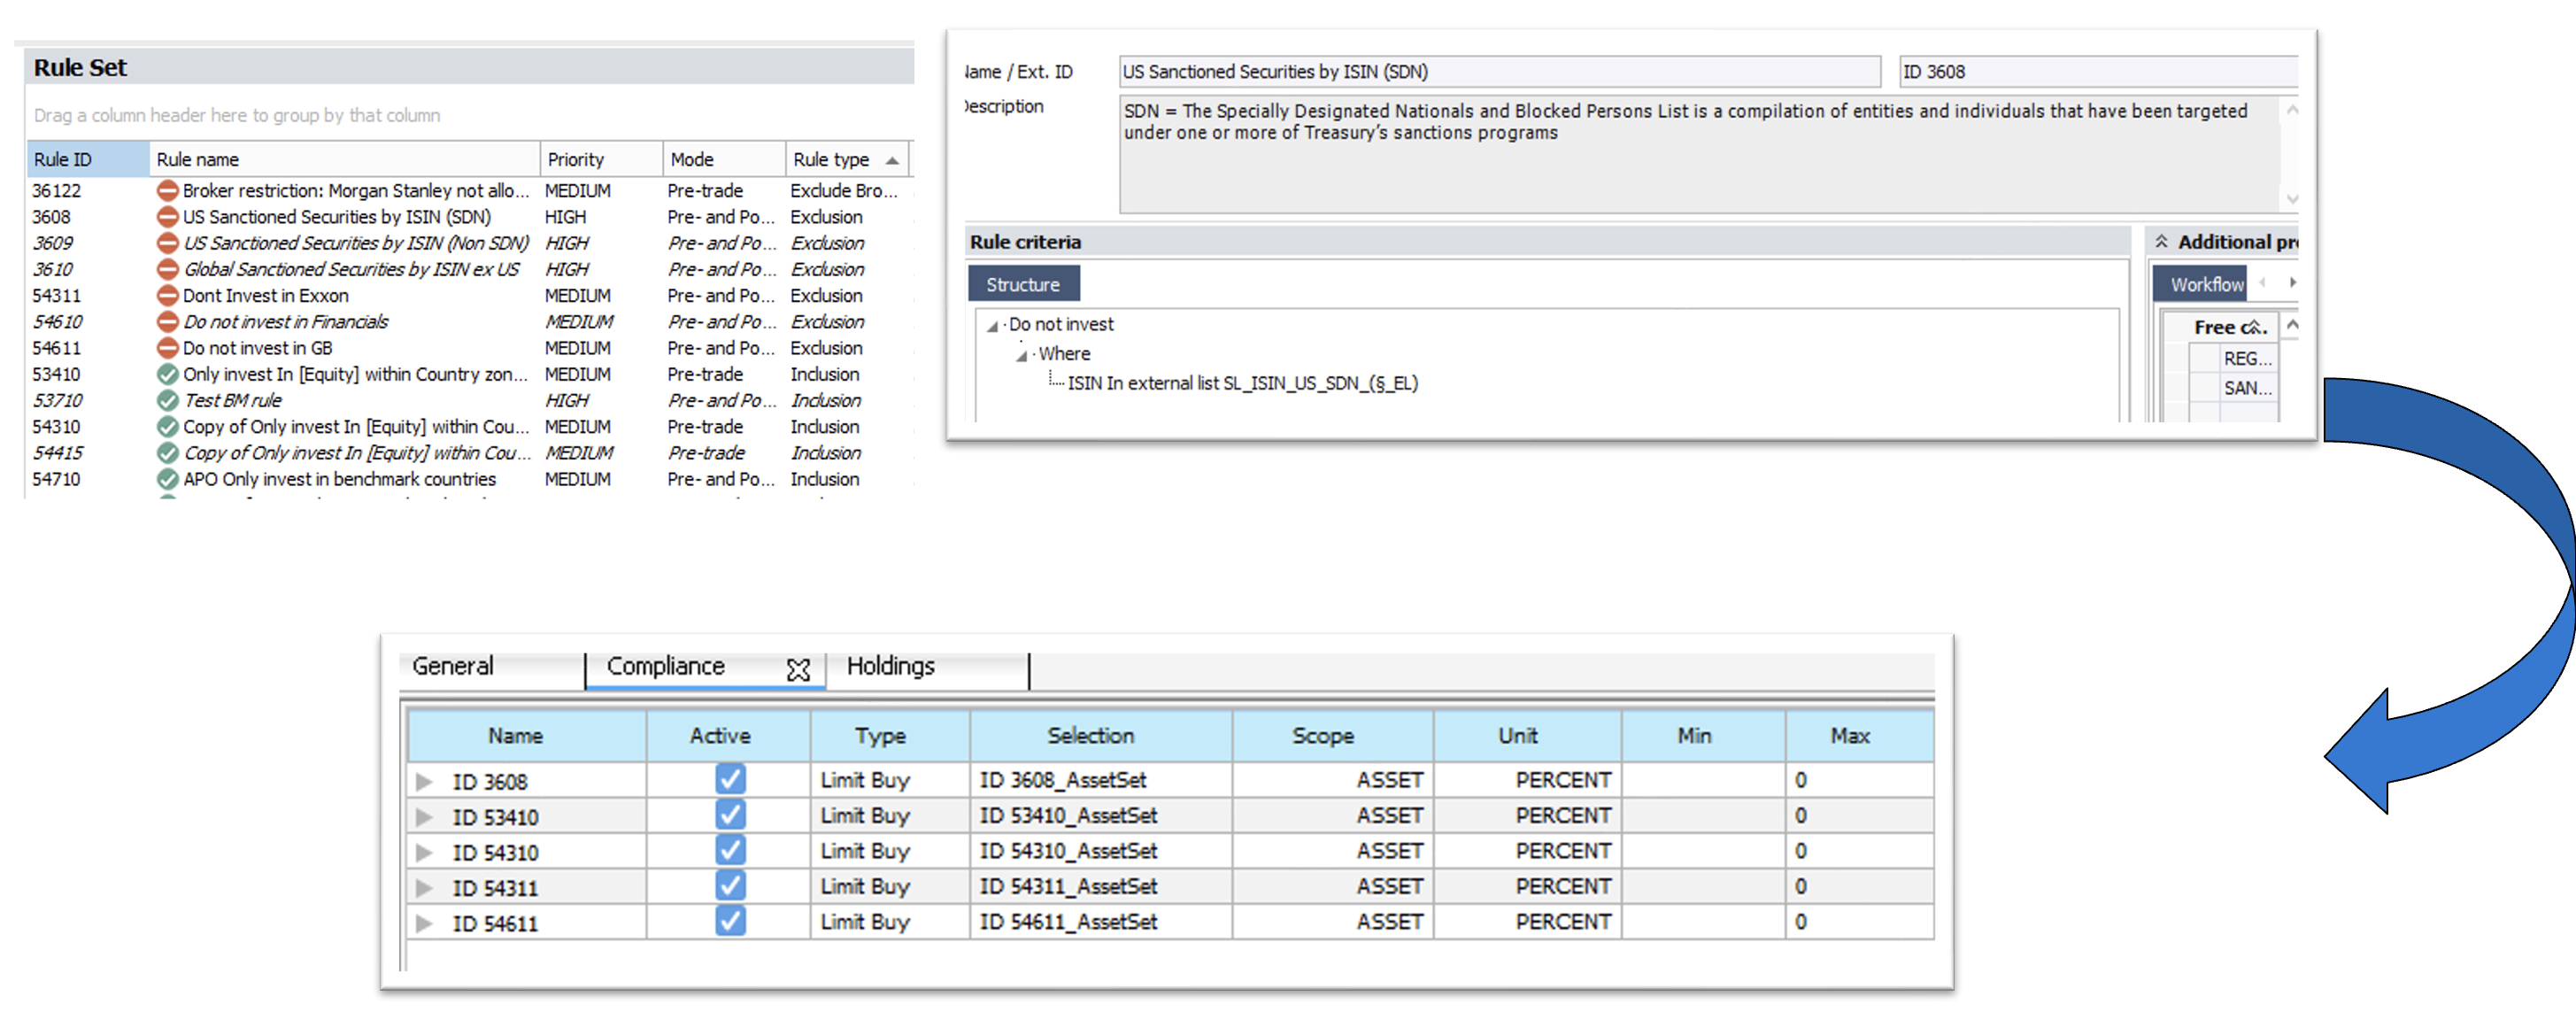
The top row of the image represents the compliance rules being managed in SimCorp Dimension, and the bottom row represents the corresponding investment constraints represented in Axioma Portfolio Optimizer. Notice the common ID that provides the link between the 2 systems.
Subscription based licensing
Axioma Portfolio Optimizer Integration
Sales module dependency
Asset Manager
Flexible Aggregations of Portfolios in Compliance Manager
Compliance Manager now offers much greater flexibility and an improved system for applying investment restrictions to sets of portfolios.
With the newly introduced concept of business entities, you can define named sets of portfolios dynamically. These sets can represent investment mandates, clients, strategies, etc., and are independent of the portfolio/portfolio group structure.
The included portfolios can change over time, with the sets able to overlap or intersect each other as needed.
In Compliance Manager, business entities are structured in a new hierarchy parallel to the existing portfolio hierarchy. This follows the well-known principles and workflow of the module, including lifecycle management, assignment of global rules and legal sets, and more.
This is an often requested addition to Compliance Manager, which has sometimes been referred to as a portfolio hierarchy without portfolio groups. We are very excited to release it with version 25.01.
Benefits
- Model portfolio structures freely in a dynamic way, independent of portfolio groups
- Improved system performance for compliance rules across large numbers of portfolio groups
- More transparent configuration of investment guideline monitoring
- Better model your investment process and structures in Compliance Manager
- Shared concept with support being rolled out to other functional areas of SimCorp Dimension in upcoming releases
Subscription based licensing
Mandates and Investment onboarding (Add-on, new)
Sales module dependency
Mandates and Investment onboarding
Strategy Tagging
Strategy tagging provides a flexible a way to group simulations, orders, and transactions, enabling portfolio managers to analyze investment decisions over time.
Traditional grouping methods in portfolio management often rely on accounting-focused split fields, which, while effective, may not fully capture the dynamic nature of opportunistic decisions. This highlights the potential for more innovative approaches that better represent pair trades, long-short strategies, bets on the macroeconomic events, credit spread strategies, etc. With the new module, you can analyze strategy tags in isolation, compare strategy tags to evaluate the different decisions, and learn from the strategy tag results.
Strategy tagging was developed with an API-first approach. A full maintenance workflow can be undertaken by using the Strategy Tagging API. Additionally, you can perform some strategy tagging tasks by using the Strategy Tags window and Strategy Tag Assignments applet in Asset Manager.
You can leverage a set of pre-defined strategy tags or create new ones on-the-fly to group simulations, orders, or transactions effectively. The flexibility of the strategy tagging approach allows you to allocate the full or partial nominal to a strategy tag, facilitating the division of an order across multiple strategies while still releasing it as a single order to the dealing desk. Strategy tagging operates independently of workflow status, allowing for swift execution and retrospective modifications.
For all transactions that are assigned to a specific strategy tag, you can request the calculation of market value, exposure, and other PKR-driven key ratios, balance book value, unrealized P/L, year-to-date P/L, and other standard accounting values, as well as associated cash flows. The cash effects of coupons and dividends are projected by using the assigned nominals of transaction assignments that can differ from the IBOR records.
Benefits
- Enables playground for portfolio managers to track their decisions and learn
- Supports active portfolio management strategies
- Optimizes impact on accounting view
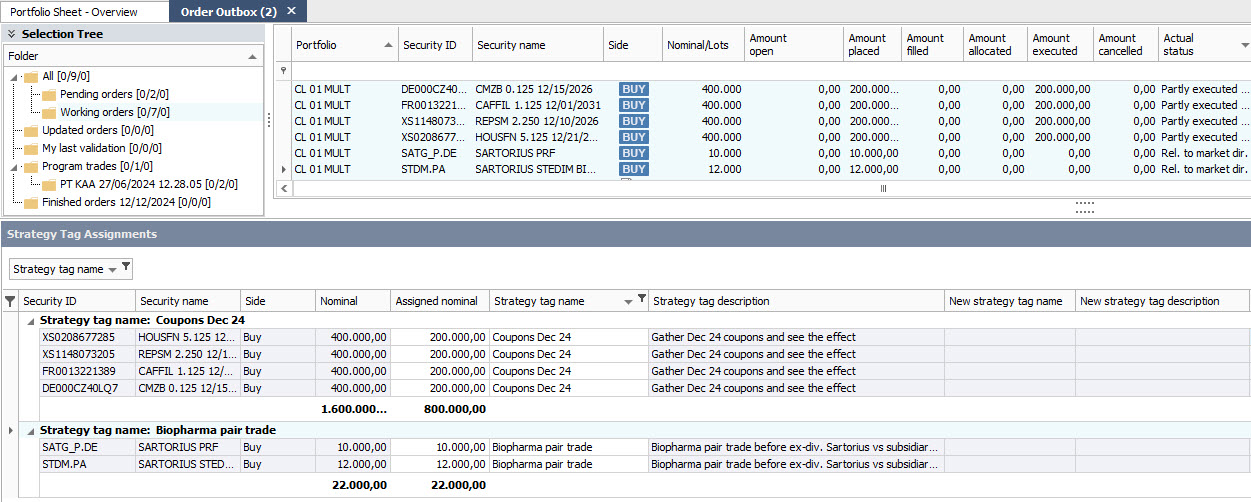
A new Strategy Tag Assignments applet in Asset Manager
Subscription based licensing
Add-On Package (for SBL): Strategy Tagging API
Sales Module (for MBL): Strategy Tagging API
Sales module dependency
Asset Manager module increases the value
CS01 calculation supported natively
In version 25.01, DV01 – the dollar value of a 1 basis point key ratio, measuring the interest rate sensitivity of a bond or portfolio of bonds, or fixed income instruments in general, became natively available in Asset Manager and elsewhere in Simcorp Dimension.
The native support for fixed income analytics has now been expanded to include CS01. CS01 captures the change in dirty price due to a 1 basis point shift in the discounting curve, whereas DV01 measures the 1 basis point shift in both the fixing and discounting curves.
CS01 serves the same purpose as the spread duration key ratio and is, in fact, defined as a simple scaling of Spread Duration – except for callable bonds, where CS01 is based on yield to worst date calculation logic.
Previously, CS01 was modeled using User Defined Key Ratios (UDKRs). Native support for CS01 removes some limitations associated with UDKRs. For example, it is now possible to use CS01 as a target key ratio in the automated position weight adjustment in Asset Manager.
Benefits
- Reduces configuration maintenance by using CS01 as a native key ratio.
- Allows CS01 to be targeted as a key ratio in Asset Manager
- Follows best practices by using SimCorp’s standard CS01 key ratios, which are applicable for bonds, swaps, index bonds, and more.
Subscription based licensing
Asset Manager
Sales module dependency
Asset Manager